Virtual currency is a digital medium of exchange that can function like money but does not have the legal status of sovereign currency. FinCEN says virtual currency is a medium of exchange that can operate like currency but does not have all the attributes of “real” currency, including legal tender status, and that convertible virtual currency (CVC) is a type of virtual currency that either has an equivalent value as currency or acts as a substitute for currency.
Key Takeaways
- Virtual Currency Is a Digital Representation of Value
- Virtual Currency Is Distinct From Traditional Fiat Currency
- Convertible Virtual Currency Can Be Exchanged for Fiat or Other Digital Assets
- Cryptocurrencies Are a Major Form of Virtual Currency
- Virtual Currency Can Enable Rapid Cross-Border Value Transfer
- Blockchain Transactions Can Provide Persistent Transaction Records
- Pseudonymity Does Not Necessarily Mean Anonymity
- Virtual Currency Can Be Used for Legitimate Payments, Investment and Value Transfer
- Criminals Can Exploit Virtual Currency for Money Laundering
- Ransomware Payments Frequently Involve Virtual Assets
- Fraud and Scam Proceeds Can Be Converted Into Virtual Currency
- Darknet Markets Have Historically Used Virtual Currency for Settlement
- Mixers and Other Obfuscation Techniques Can Complicate Transaction Tracing
- Self-Hosted Wallets Can Reduce Reliance on Centralised Intermediaries
- Virtual Asset Service Providers Can Act as Important Financial Crime Control Points
- Blockchain Analytics Can Strengthen Transaction Monitoring
- Wallet Attribution Can Connect On-Chain Activity With Real-World Entities
- Sanctions Risk Can Extend to Virtual Currency Addresses and counterparties
- Fiat-to-Crypto and Crypto-to-Fiat Conversion Points Are Critical Risk Areas
- Effective Virtual Currency Controls Require Integration of On-Chain and Off-Chain Intelligence
In the financial crime environment, virtual currency matters because it allows value to be stored, transferred, and exchanged digitally outside traditional payment rails. That creates legitimate uses, but also distinct risks around money laundering, fraud, sanctions evasion, ransomware proceeds, scam payments, and cross-border movement of value. FATF now generally uses the term virtual assets (crypto assets) for digital representations of value that can be traded, transferred, or used for payment, and explicitly says this category does not include digital representations of fiat currencies.
From a professional perspective, “virtual currency” is an older but still important term, especially in U.S. FinCEN guidance, while virtual asset has become the broader international standard in FATF materials. That distinction matters because firms may still encounter both labels in policy, law, and operations. FinCEN continues to use virtual currency and CVC terminology in its regulatory guidance, while FATF frames the modern risk landscape through virtual assets and virtual asset service providers.
Watch on YouTube: Virtual Currency
A key reason virtual currency is significant is that it combines speed, digital transferability, and cross-border reachwith varying degrees of transparency or opacity depending on the asset, wallet structure, and service provider. In the financial crime environment, that means virtual currency can be used for legitimate investment and payment activity, but it can also be used to move proceeds of fraud, obscure fund flows, or bypass traditional intermediary controls. FATF’s updated virtual asset guidance says jurisdictions must assess and mitigate the risks associated with virtual asset activity and subject providers to relevant AML/CFT measures.
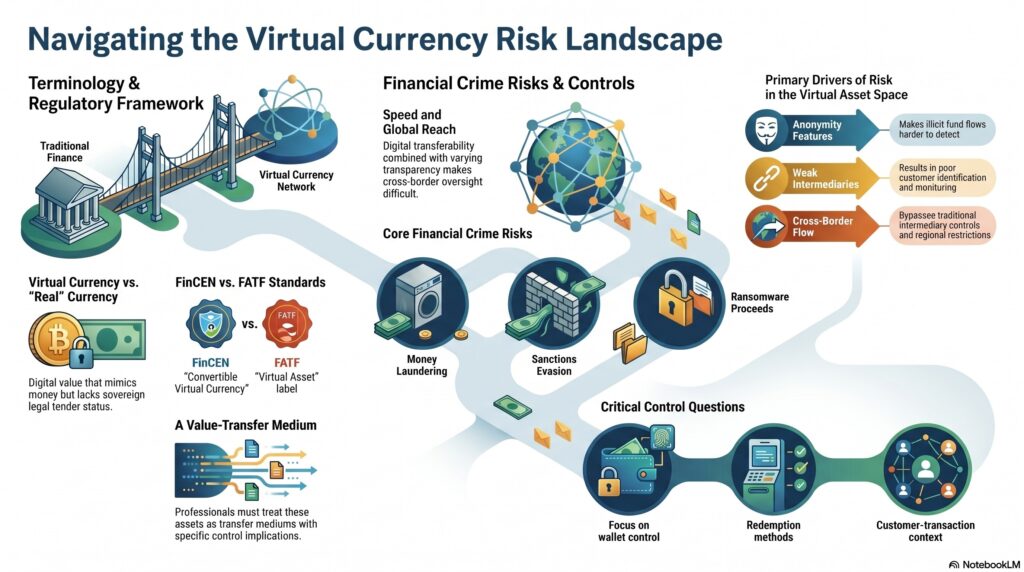
This is why virtual currency is closely linked to AML and sanctions controls. The financial crime concern is not simply that the asset is digital. The concern is whether the activity involves anonymity-enhancing features, weak intermediary oversight, poor customer identification, or cross-border flows that make illicit activity harder to detect. FATF’s virtual asset materials stress that virtual asset service providers should be subject to the same relevant AML/CFT measures that apply to financial institutions.
A mature professional view therefore treats virtual currency as a value-transfer medium with specific control implications, not just as a technology label. The key questions are who controls the wallet or account, how the asset is acquired and redeemed, whether an intermediary is involved, what screening and monitoring exist, and whether the customer and transaction make sense in context. In regulatory practice, those questions now sit increasingly within the broader virtual-asset framework, even where the older term virtual currency remains in use.
What Financial Institutions Should Consider
- Include Virtual Currency in Enterprise-Wide Financial Crime Risk Assessments
- Identify Customer Exposure to Virtual Asset Activity
- Understand the Purpose of Crypto-Related Transactions
- Assess Virtual Asset Service Provider Counterparties
- Apply Risk-Based Due Diligence to Crypto Businesses
- Integrate Blockchain Analytics Into Transaction Monitoring
- Screen Relevant Wallet Addresses for Sanctions Exposure
- Identify Links to Mixers and Obfuscation Services
- Monitor Exposure to Ransomware-Associated Addresses
- Detect Links to Fraud and Scam Infrastructure
- Assess Source of Funds for Significant Crypto Transactions
- Strengthen Source of Wealth Reviews for Material Virtual Asset Holdings
- Analyse Fiat-to-Crypto and Crypto-to-Fiat Flows
- Monitor Rapid Movement Between Multiple Wallets and Platforms
- Apply Network Analytics to Connected Wallets and entities
- Assess Self-Hosted Wallet Risk Contextually
- Integrate Crypto Intelligence With Traditional Transaction Monitoring
- Maintain Appropriate Travel Rule Controls Where Applicable
- Train Investigators in Blockchain Transaction Analysis
- Treat Virtual Currency as a Distinct Financial Crime Ecosystem Rather Than a Conventional Payment Product
Ultimately, virtual currency is important in the financial crime environment because it represents digital value that can mimic some functions of money without being sovereign legal tender. That makes it commercially significant and also a major focus for AML, sanctions, fraud, and regulatory controls.