Spoofing and layering are manipulative trading practices in which orders are placed without a genuine intention to execute them, in order to create a false impression of supply, demand, or market depth and influence price or execution. The CFTC states that spoofing includes submitting bids or offers with the intent to cancel before execution and identifies conduct such as creating false market depth or artificial price movements. ESMA’s market-abuse materials describe layering and spoofing as submitting multiple or large orders, often away from the touch on one side of the order book, in order to execute a trade on the other side, after which the non-genuine orders are removed.
Key Takeaways
- Spoofing and Layering Are Forms of Market Manipulation
- Spoofing Uses Non-Genuine Orders Intended to Be Cancelled Before Execution
- Layering Commonly Uses Multiple Orders at Different Price Levels
- False Orders Can Create Artificial Impressions of Supply or Demand
- Manipulative Orders Can Distort Apparent Market Depth
- The Objective Is Often to Influence Price for a Genuine Opposite-Side Trade
- Non-Bona Fide Orders Can Affect Other Market Participants’ Decisions
- Short-Lived Orders Can Still Manipulate Electronic Markets
- Algorithmic Trading Can Increase the Speed and Scale of Spoofing Strategies
- Order Cancellation Alone Does Not Establish Manipulation
- Intent Is Central to Distinguishing Spoofing From Legitimate Trading
- Repeated Placement and Rapid Cancellation Can Be a Key Indicator
- Opposite-Side Executions Can Strengthen the Manipulation hypothesis
- Large Visible Orders Can Be Used to Create Artificial Buying or Selling Pressure
- Spoofing and Layering Can Distort Price Discovery
- Market Abuse Can Occur Without Inside Information
- Order-Book Data Is Critical to Detecting Manipulative Patterns
- Communications Can Help Establish Trading Intent
- Regulators Continue to Treat Spoofing and Layering as Active Enforcement Risks
- Effective Detection Requires Pattern-Based Order Surveillance Rather Than Review of Individual Trades Alone
In the financial crime environment, these practices matter because they are forms of market manipulation. They do not depend on misusing inside information; instead, they distort market signals by making the order book look different from the trader’s real intention. The FCA states that market manipulation can amount to market abuse, and its Market Conduct sourcebook continues to refer specifically to practices known as layering and spoofing.
From a professional perspective, the distinction is usually this: spoofing is the broader concept of placing non-bona fide orders with intent to cancel, while layering is a common spoofing pattern involving multiple orders at different price levels to create a stronger false impression of depth or pressure. The CFTC’s enforcement materials describe “layered spoof orders” as a pattern used to manipulate prices so that a genuine order is filled at an artificial price.
Watch on YouTube: Spoofing and Layering
The purpose of spoofing and layering is usually to move the market just enough to benefit a genuine order on the other side. A trader may place false sell orders to push price downward and buy more cheaply, or place false buy orders to push price upward and sell at a better level. Once the genuine order is executed, the deceptive orders are cancelled. ESMA’s examples and the CFTC’s interpretations both reflect this structure.
This is why spoofing and layering are especially important in electronic and algorithmic markets. These strategies exploit the speed and visibility of the order book, where even short-lived orders can influence other participants’ behavior, pricing models, and execution decisions. ESMA has explicitly noted that new manipulation strategies can be implemented using algorithms, including spoofing and layering.
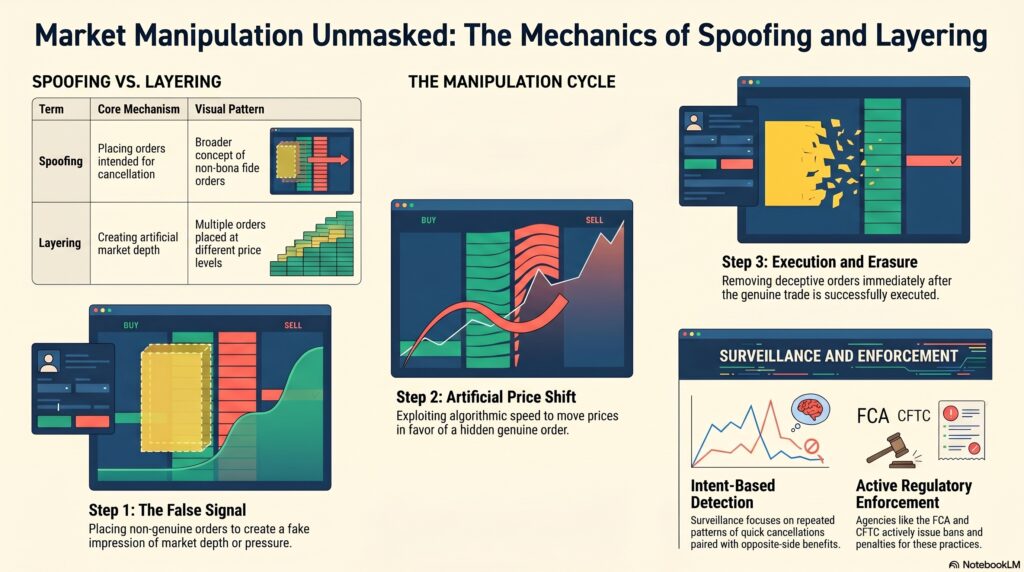
For firms, the control challenge is largely one of surveillance and intent inference. A single cancelled order is not misconduct by itself. What becomes suspicious is a repeated pattern of large visible orders being placed and cancelled quickly, especially when opposite-side trades benefit and the behavior lacks a credible execution rationale. The FCA’s sourcebook notes that such indicators do not automatically prove market abuse, but they are important signals for surveillance and escalation.
Regulators continue to treat spoofing and layering as live enforcement risks. The FCA referred suspected orderbook spoofing and layering cases into Enforcement, and in July 2025 the Upper Tribunal upheld the FCA’s bans against three bond traders for market manipulation. The CFTC also continues to report spoofing-related enforcement as part of its broader market-manipulation program.
What Financial Institutions Should Consider
- Maintain Dedicated Spoofing and Layering Surveillance Scenarios
- Monitor Large Orders Cancelled Shortly After Placement
- Detect Repeated High Cancellation-to-Execution Ratios
- Analyse Orders Placed Away From the Best Bid or Offer
- Identify Multiple Orders Across Successive Price Levels
- Monitor Genuine Trades Executed on the Opposite Side
- Correlate Order Placement With Subsequent Price Movement
- Detect Repeated Patterns Across Trading Sessions
- Compare Behaviour With the Trader’s Historical Profile
- Monitor Activity Across Related Instruments and Venues
- Strengthen Order-Book Surveillance
- Integrate Trade and Communications Surveillance
- Review Algorithmic and Automated Trading Strategies
- Monitor Rapid Order Entry, Modification and Cancellation
- Assess Whether Trading Behaviour Has a Credible Execution Rationale
- Apply Network Analysis to Connected Accounts Where Relevant
- Maintain Clear Market Abuse Escalation Standards
- Preserve Complete Order, Trade and Communications Audit Trails
- Feed Confirmed Cases Back Into Surveillance Calibration
- Treat Spoofing and Layering Detection as an Intent-Inference and Pattern-Recognition Challenge
Ultimately, spoofing and layering matter in the financial crime environment because they corrupt one of the market’s core trust mechanisms: the assumption that visible orders reflect genuine trading interest. By creating false market signals, they distort price discovery, harm counterparties and investors, and undermine market integrity. For that reason, they should be treated as serious market-abuse risks requiring strong order-book surveillance, communications review, and governance over trading behavior.