A money order is a prepaid negotiable instrument used to make a payment for a fixed amount. USPS describes money orders as a safer alternative to cash and personal checks, and Cornell’s Legal Information Institute defines a money order as a prepaid negotiable instrument that can be purchased from banks, post offices, and other businesses, usually subject to face-value limits.
Key Takeaways
- Money Orders Are Prepaid Negotiable Payment Instruments
- Money Orders Provide an Alternative to Cash and Personal Checks
- Money Orders Sit Between Cash and Fully Account-Based Payments
- Their Prepaid Nature Can Make Them Attractive for Legitimate Retail Payments
- Monetary Instrument Rules Can Apply to Certain Money Orders
- Cash Purchases of Money Orders Can Create AML Risk
- Money Orders Can Be Used to Convert Cash Into More Portable Value
- Repeated Money Order Purchases Can Support Structuring
- Multiple Purchases Below Reporting Thresholds Can Be Suspicious
- Money Orders Can Be Used to Move Value Without Traditional Bank Transfers
- Fraudsters Can Use Counterfeit or Fraudulent Money Orders
- Scam Victims Can Be Instructed to Purchase and Send Money Orders
- Money Order Activity Must Be Assessed Against Customer Profile and Economic Purpose
- Rapid Conversion of Cash Into Money Orders Can Increase Risk
- Money Orders Are Not Inherently Suspicious
- Product Risk Depends on Behaviour, Frequency, Value and Context
- Money Orders Can Be Relevant to Both AML and Fraud Monitoring
- Strong Recordkeeping and Identification Controls Are Critical
- Money Orders Remain Financial Crime-Relevant Despite Being an Older Payment Product
- Effective Controls Should Focus on Patterns Rather Than the Instrument Alone
In the financial crime environment, money orders matter because they sit between cash and fully account-based payments. They are legitimate and widely used, but they can also be attractive in fraud and money-laundering contexts because they can convert cash into a more portable, more acceptable, and sometimes less transparent payment instrument. Under the U.S. BSA framework, certain money orders are included within the broader regulatory concept of monetary instruments, which is why they appear in AML recordkeeping and reporting rules.
Watch on YouTube: Money Order
From a professional perspective, the significance of a money order is not that it is inherently suspicious. The significance is that it can be used as a cash-equivalent instrument in ways that reduce immediate visibility compared with ordinary account-to-account transfers. FinCEN guidance states that financial institutions must verify identity and retain records before issuing or selling money orders purchased with currency in amounts between $3,000 and $10,000 inclusive, which reflects the recognized AML risk in this product category.
Money orders are therefore relevant in several financial crime scenarios. They may be used to make payments that appear more secure or more formal than cash, to structure purchases below reporting thresholds, to fund scams, or to move value across parties without using a traditional bank transfer. They also appear in fraud schemes where victims are sent fraudulent money orders or persuaded to purchase and send them. The FFIEC’s red-flag materials emphasize that banks should look for suspicious patterns associated with money laundering and terrorist financing, and money-order activity can be part of those patterns when it is inconsistent with customer profile or economic purpose.
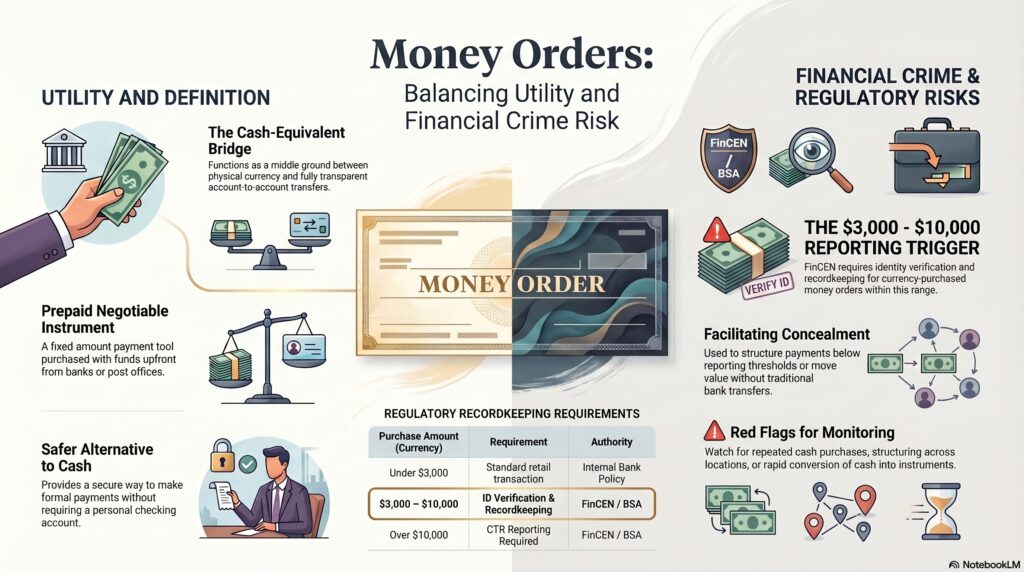
For firms, the control issue is usually context. A money order purchased for a normal personal payment may present little concern. Repeated purchases with currency, use by customers with no clear legitimate need, structuring across multiple locations or days, or rapid conversion of cash into negotiable instruments can all increase risk. Because money orders can function as a bridge between cash and negotiable payment, they remain operationally important in AML, fraud, and customer-risk monitoring even though they are an older payment product.
What Financial Institutions Should Consider
- Monitor Repeated Cash Purchases of Money Orders
- Detect Structuring Across Multiple Money Order Transactions
- Aggregate Related Purchases Across Locations and Channels
- Review Activity Just Below Relevant Reporting Thresholds
- Verify Customer Identity Where Required
- Maintain Required Monetary Instrument Records
- Compare Money Order Purchases With Expected Customer Behaviour
- Identify Customers With No Clear Economic Need for Repeated Purchases
- Monitor Third-Party Funding of Money Orders
- Review Multiple Instruments Purchased in Short Timeframes
- Detect Rapid Cash-to-Instrument Conversion
- Monitor Unusual Beneficiary or Payee Patterns
- Identify Frequent Cancellation or Refund Activity
- Strengthen Controls Around Fraudulent Money Orders
- Train Staff to Recognise Money Order Scam Typologies
- Integrate Money Order Activity Into Transaction Monitoring
- Connect Cash, Monetary Instrument and Account Activity
- Apply Enhanced Due Diligence Where Usage Creates Higher Risk
- Maintain Clear Escalation Procedures for Suspicious Patterns
- Treat Money Order Monitoring as Part of Broader Monetary Instrument Risk Management
Ultimately, a money order is a legitimate prepaid payment instrument, but in the financial crime environment it is also a product that can facilitate concealment, structuring, and movement of value if controls are weak. For that reason, money orders should be understood not just as a retail payment convenience, but as a payment instrument with specific AML and fraud-control relevance.