Wash trading is the practice of entering into transactions that create the appearance of genuine trading activity without a real change in beneficial ownership or market risk. ESMA’s market-abuse materials define wash trades as arrangements for the sale or purchase of a financial instrument where there is no change in beneficial interests or market risk, or where any transfer is only between parties acting in concert or collusion. In U.S. commodities regulation, the CFTC glossary describes wash trading as a scheme that gives the appearance of trading when no bona fide, competitive tradehas actually occurred.
Key Takeaways
- Wash Trading Creates the Appearance of Genuine Market Activity Without Meaningful Change in Beneficial Ownership
- Wash Trades Can Artificially Inflate Trading Volume
- Artificial Volume Can Mislead Other Market Participants About Liquidity
- Wash Trading Can Distort Price Discovery
- Self-Trading Is a Common Wash Trading Indicator
- Coordinated Trading Between Related Accounts Can Replicate the Effect of Self-Trading
- Beneficial Ownership Analysis Is Critical to Identifying Hidden Connections
- Wash Trading Can Be Used to Support Broader Market Manipulation Strategies
- Cryptoasset Markets Can Be Particularly Exposed Where Surveillance Is Weak
- Repeated Matching of Similar Order Size, Price and Timing Can Be Suspicious
- High Cancellation and re-entry activity Can Accompany Manipulative Trading
- Economic Substance Is Central to Distinguishing Genuine Trades From Wash Activity
- Individual Trades May Appear Legitimate When Viewed in Isolation
- Cross-Account and Cross-Venue Analysis Can Reveal Hidden Wash Patterns
- Algorithmic Trading Can Increase the Speed and Complexity of Wash Trading
- Communications Can Provide Evidence of Coordination and intent
- Trade Surveillance Must Focus on Patterns Rather Than Isolated executions
- Wash Trading Can Create Both Market Abuse and conduct risk
- Regulators Treat Artificial Trading Activity as a Market Integrity concern
- Effective Detection Requires Trading, ownership and network intelligence
In the financial crime environment, wash trading matters because it is a form of false market activity. It creates the impression of liquidity, volume, price interest, or market participation that is not economically genuine. That can mislead other market participants, distort price formation, support manipulation, and undermine confidence in the fairness of markets. The FCA states that the UK Market Abuse Regulation aims to increase market integrity and investor protection, which is the broader framework within which wash trading is treated as problematic.
From a professional perspective, the key issue is economic reality. A legitimate trade normally transfers ownership or risk between parties with genuinely different economic interests. A wash trade does not do that in substance. The trade may appear valid in form, but it lacks real market purpose because the same beneficial owner, or coordinated parties with aligned interests, end up on both sides in a way that neutralizes genuine market exposure. ESMA’s definition is explicit that the problem is the absence of meaningful change in beneficial interest or market risk.
Watch on YouTube: Wash Trading
This is why wash trading is closely associated with market manipulation. A trader or group may use wash trades to inflate reported volume, create the illusion of demand, support a desired price level, or give credibility to a security, contract, or market that would otherwise appear inactive. In some environments, wash trading can also be used to support wider schemes such as pump-and-dump activity, misleading valuation, or fee/rebate abuse. This is an inference supported by ESMA’s classification of wash trades under false or misleading transactions and by the CFTC’s treatment of wash trading as fictitious trading.
Wash trading is especially important in electronic and fragmented markets, where large numbers of transactions can occur quickly and apparent volume can influence investor perception or trading algorithms. The underlying misconduct is not limited to traditional securities markets. U.S. derivatives enforcement remains active, with the CFTC issuing wash-sale enforcement actions in 2024 and 2025 involving non-competitive transactions and wash sales. That shows the typology remains current, not historical.
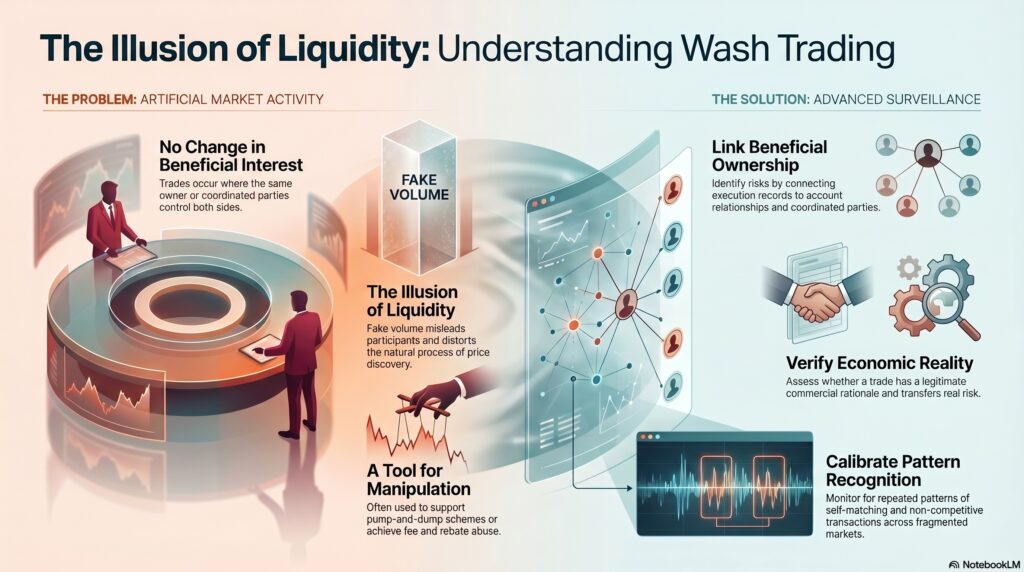
For firms, the control challenge is that a wash trade may not always be obvious from a single execution record. Detection often depends on linking counterparties, beneficial ownership, account relationships, timing, pricing, and repeated patterns of self-matching or coordinated trading. Where the same person controls both sides, or related parties repeatedly transact without real economic change, the risk becomes much more significant. This is an inference supported by the regulatory definitions focusing on beneficial ownership, market risk, and non-bona fide trading.
A mature surveillance framework therefore needs to look beyond superficial execution data. It should assess whether the trade had a legitimate commercial rationale, whether risk truly changed hands, whether the counterparties were genuinely independent, and whether the activity formed part of a wider manipulative pattern. Trade surveillance, beneficial ownership understanding, and escalation into market-abuse reporting processes are all relevant here. ESMA’s broader market-abuse reporting work highlights the importance of typologies and suspicious transaction and order reporting in this area.
What Financial Institutions Should Consider
- Maintain Dedicated Wash Trading Surveillance Scenarios
- Detect Self-Matching and Self-Trading Activity
- Monitor Trades Between Related Accounts
- Analyse Common Beneficial Ownership Across Counterparties
- Compare Order Size, Price and Timing for Repeated Matches
- Monitor Rapid Buy-and-Sell Activity With Limited Economic Exposure
- Detect Repeated Transactions With No Clear Investment Rationale
- Strengthen Cross-Account Surveillance
- Apply Cross-Venue Surveillance Where Relevant
- Use Network Analytics to Identify Connected Traders and Accounts
- Integrate Beneficial Ownership Data Into Surveillance
- Monitor Algorithmic Trading for Self-Interaction
- Correlate Trade and Communications Surveillance
- Review Unusual Volume Spikes
- Assess Whether Trading Creates Artificial Liquidity
- Maintain Clear Market Abuse Escalation Standards
- Preserve Complete Order and Trade Audit Trails
- Feed Confirmed Cases Back Into Surveillance Calibration
- Conduct Regular Wash Trading Scenario Testing
- Treat Wash Trading Detection as a Beneficial-Ownership and Pattern-Recognition Challenge
Ultimately, wash trading matters in the financial crime environment because it creates fake market activity. It undermines market integrity by making trading interest, volume, or price action look real when it is not. For that reason, it should be treated as a serious market-abuse and surveillance risk requiring strong data linkage, ownership transparency, and well-calibrated trade monitoring.