The USA PATRIOT Act is the post-September 11, 2001 U.S. law that significantly expanded the anti-money laundering and counter-terrorist-financing framework applying to the financial system. FinCEN’s official summary says the Act was intended to strengthen U.S. measures to prevent, detect, and prosecute international money laundering and terrorist financing, subject higher-risk foreign jurisdictions and institutions to special scrutiny, require broader reporting of potential money laundering, and make records more useful to investigators.
Key Takeaways
- The USA PATRIOT Act Significantly Expanded U.S. Anti-Money Laundering and Counter-Terrorist Financing Requirements
- Title III Is Commonly Known as the International Money Laundering Abatement and Anti-Terrorist Financing Act
- The Act Strengthened the Bank Secrecy Act Framework
- Customer Identification Program Requirements Were Expanded Through Section 326
- Correspondent Banking Due Diligence Was Strengthened
- Private Banking Relationships Became Subject to Enhanced Scrutiny
- Shell Bank Relationships Were Specifically Restricted
- Section 311 Created Powerful Special Measures Against Primary Money Laundering Concerns
- Section 314 Supports Information Sharing Between Government and Financial Institutions
- Section 314(b) Enables Voluntary Information Sharing Among Eligible Financial Institutions
- Financial Institutions Must Maintain Risk-Based AML Controls
- Beneficial Ownership and Customer Transparency Became Increasingly Important Within the Wider U.S. AML Framework
- Cross-Border Banking Relationships Receive Particular Scrutiny
- Terrorist Financing Risk Is Embedded Within the Act’s AML Objectives
- The Act Increased the Importance of Customer and Counterparty Identification
- Recordkeeping and Investigative Cooperation Requirements Were Strengthened
- Regulatory and Law Enforcement Access to Financial Intelligence Was Expanded
- USA PATRIOT Act Compliance Requires Coordination Across AML, Legal and Operations Functions
- The Act Remains a Foundational Component of the U.S. Financial Crime Regulatory Framework
- Effective Compliance Requires Understanding Both the Statutory Provisions and the Broader BSA/AML Regime
In the financial crime environment, the significance of the USA PATRIOT Act is that it reshaped AML from a narrower reporting framework into a more expansive risk-based, intelligence-linked control regime. Its importance is not just historical. Many of the core concepts still used in financial crime compliance today — customer identification, correspondent banking due diligence, information sharing, and stronger institutional AML obligations — were materially reinforced or operationalized through the Act and its implementing rules.
From a professional perspective, one of the Act’s most important legacies is Section 326, which led to the modern Customer Identification Program (CIP) requirement. FinCEN’s official CIP guidance says the final CIP rule implements Section 326 of the USA PATRIOT Act and requires covered financial institutions to maintain a Customer Identification Program. In practical terms, this helped formalize the idea that firms must verify enough about a customer’s identity at onboarding to support a credible AML framework.
Watch on YouTube: USA PATRIOT Act
Another major provision is Section 312, which requires due diligence — and in some cases enhanced due diligence — for certain foreign correspondent accounts and private banking accounts. The FFIEC says the goal of Section 312 is to help prevent money laundering through accounts that give foreign financial institutions a base for moving funds through the U.S. financial system. This remains highly relevant because correspondent banking is one of the main channels through which cross-border illicit finance can move if transparency and oversight are weak.
The Act is also central because of Section 314, especially 314(a) and 314(b). FinCEN’s current materials explain that Section 314(a) enables law enforcement, through FinCEN, to reach out to certain financial institutions to locate accounts and transactions linked to investigative subjects, while Section 314(b) permits financial institutions, after notifying Treasury, to share information with one another to identify and report activity that may involve money laundering or terrorist activity. In the financial crime environment, that is a major shift toward making AML more intelligence-driven and collaborative rather than purely institution-by-institution.
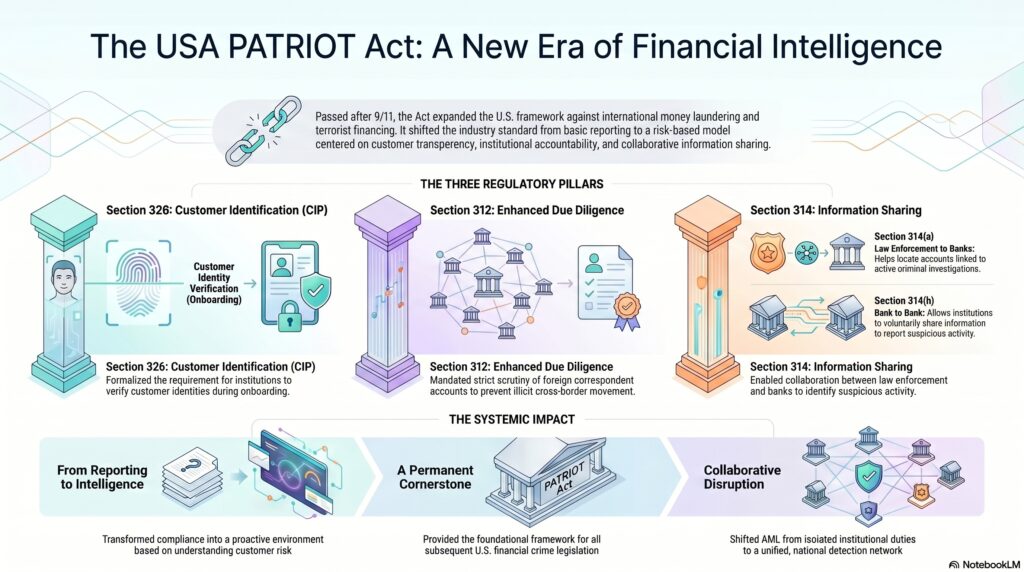
This is why the USA PATRIOT Act matters beyond any single provision. It helped push financial crime compliance toward a model based on customer transparency, higher-risk account scrutiny, broader AML program obligations, and structured information sharing. The result was a more proactive control environment in which institutions were expected not only to file reports, but to understand customers, identify risk, and cooperate in disrupting illicit finance. This is an inference supported by FinCEN’s official summary of the Act’s objectives and by the implementing guidance for Sections 312, 314, and 326.
It is also important to place the Act in today’s context. The USA PATRIOT Act remains foundational, but it no longer stands alone. Later legislation, including the Anti-Money Laundering Act of 2020, built on and updated the U.S. AML framework rather than replacing the PATRIOT Act’s core legacy. That means the PATRIOT Act is best understood as a cornerstone of the modern U.S. financial crime regime, especially in relation to AML, terrorist financing prevention, correspondent banking controls, and information sharing.
What Financial Institutions Should Consider
- Maintain Effective Customer Identification Program Controls
- Verify Customer Identity Using Risk-Based Procedures
- Strengthen Correspondent Banking Due Diligence
- Prohibit Relationships With Shell Banks Where Required
- Apply Enhanced Due Diligence to Higher-Risk Private Banking Relationships
- Assess Foreign Correspondent Ownership and Control
- Maintain Procedures for Section 314(a) Information Requests
- Establish Controlled Processes for Section 314(b) Information Sharing
- Protect Confidential Information Shared Under Applicable Provisions
- Integrate Terrorist Financing Risk Into AML Monitoring
- Maintain Effective Cross-Border Payment Monitoring
- Identify Higher-Risk Foreign Financial Institution Relationships
- Maintain Accurate Customer and Counterparty Records
- Escalate Relationships Involving Primary Money Laundering Concerns
- Integrate PATRIOT Act Requirements Into the Wider BSA/AML Framework
- Train Relevant Staff on Applicable PATRIOT Act Obligations
- Maintain Complete Compliance and Investigation Audit Trails
- Monitor FinCEN and U.S. Regulatory Guidance
- Review Controls Following Material Regulatory or Legislative Change
- Treat PATRIOT Act Compliance as a Core U.S. Financial Crime Governance Requirement
Ultimately, the USA PATRIOT Act matters in the financial crime environment because it transformed how the U.S. financial system is expected to prevent and detect illicit finance. It strengthened onboarding controls, expanded scrutiny of higher-risk relationships, enabled broader information sharing, and reinforced the role of financial institutions as active participants in national financial crime detection and disruption.