Structuring is the act of breaking up transactions to evade legal reporting or recordkeeping requirements. FinCEN says structuring is the breaking up of transactions for the purpose of evading Bank Secrecy Act reporting and recordkeeping requirements, and the FFIEC states that structuring transactions to evade BSA reporting and certain recordkeeping requirements can result in civil and criminal penalties.
Key Takeaways
- Structuring Deliberately Breaks Transactions Into Smaller Amounts to Avoid Detection or Reporting
- Structuring Is Commonly Associated With Cash Transaction Reporting Thresholds
- Structuring Can Involve Deposits, Withdrawals, Transfers or Monetary Instruments
- Multiple Transactions Can Be Split Across Different Accounts
- Different Branches or Locations Can Be Used to Reduce Visibility
- Multiple Individuals Can Be Used to Conduct Structured Transactions
- Structuring Can Form Part of the Placement Stage of Money Laundering
- Smurfing Is a Common Form of Structuring
- Transactions Just Below Reporting Thresholds Can Be a Relevant Indicator
- Repeated Small Transactions May Be More Significant Than a Single Large Transaction
- Structuring Can Occur Over Hours, Days or Longer Periods
- Legitimate Activity Can Also Produce Threshold-Like Patterns
- Intent to Evade Reporting or Monitoring Is Central to Structuring Risk
- Cash-Intensive Businesses Can Require Additional Contextual Analysis
- Money Orders and Other Monetary Instruments Can Be Used in Structuring Schemes
- Cross-Channel Activity Can Conceal the Overall Transaction Pattern
- Structuring Detection Requires Aggregation Across Accounts and Locations
- Customer Behaviour Should Be Compared With Expected Activity
- Threshold-Based Monitoring Alone Can Miss More Sophisticated Structuring
- Effective Detection Requires Pattern, Context and Relationship Analysis
In the financial crime environment, structuring matters because it is one of the clearest signs that a person may be trying to keep cash or cash-equivalent activity below regulatory visibility thresholds. The most familiar example is breaking a cash transaction that would otherwise trigger a Currency Transaction Report into smaller amounts below $10,000, whether across one day, multiple days, multiple branches, or multiple institutions. The IRS’s structuring guidance gives examples such as making deposits into multiple accounts or at multiple institutions, all below $10,000 but together above that level.
From a professional perspective, structuring is significant because the misconduct lies not only in the movement of funds, but in the intent to evade transparency requirements. A series of smaller transactions is not automatically improper. What makes it structuring is that the transactions are arranged for the purpose of avoiding reporting or recordkeeping obligations. The FFIEC’s definition and the eCFR reference both emphasize that the key element is conduct undertaken to evade CTR or related BSA requirements.
Watch on YouTube: Structuring
This is why structuring is closely linked to AML, fraud, tax evasion, and proceeds-of-crime risk. A customer who deliberately fragments transactions may be trying to place illicit cash into the financial system, disguise the scale of activity, avoid audit trails, or reduce the chance of law-enforcement attention. FinCEN’s CTR educational materials state that customers who attempt to break up transactions to evade CTR reporting face potential civil and criminal consequences.
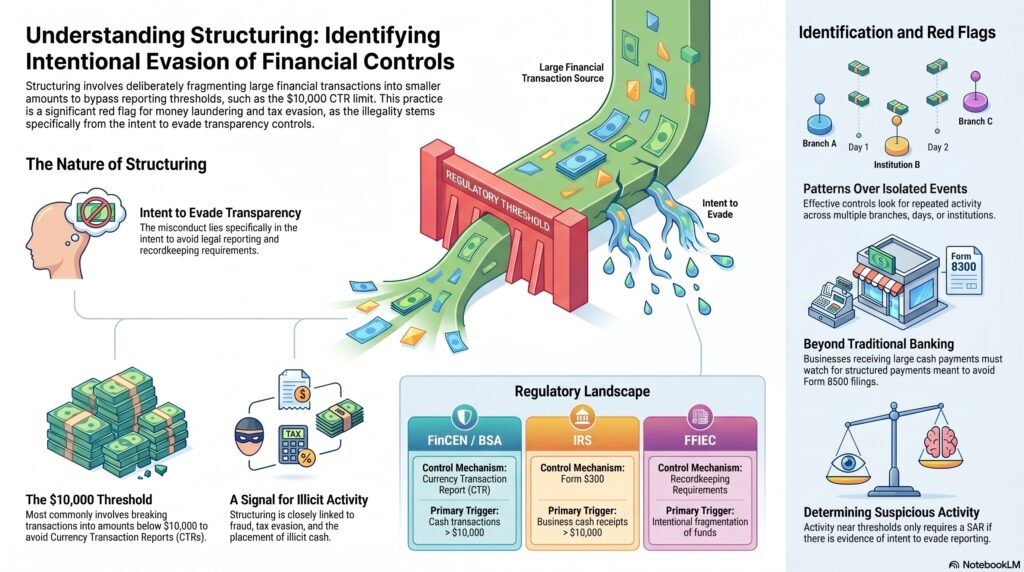
Structuring is also relevant outside traditional bank deposits. The IRS Form 8300 guidance says structuring can include breaking up large cash transactions into smaller cash transactions to disguise the true amount involved and make it appear that Form 8300 filing is unnecessary. That means the concept is important not only for banks, but also for businesses receiving reportable cash payments.
A mature control framework therefore looks for patterns rather than isolated amounts. Relevant indicators include repeated cash transactions just below reporting thresholds, transactions split across branches or entities, multiple people acting on behalf of the same source of funds, or explanations that do not match the pattern of activity. FinCEN’s October 2025 SAR FAQs also make an important point: activity merely near the CTR threshold is not, by itself, enough to require a structuring SAR without information suggesting an intent to evade reporting requirements.
What Financial Institutions Should Consider
- Aggregate Transactions Across Accounts and Channels
- Monitor Activity Across Multiple Branches and Locations
- Detect Repeated Transactions Below Reporting Thresholds
- Identify Sudden Changes in Cash Transaction Behaviour
- Monitor Multiple Depositors Linked to the Same Customer
- Detect Smurfing Across Connected Individuals
- Review Repeated Purchases of Monetary Instruments
- Monitor Structured Cash Deposits and Withdrawals
- Compare Activity With Expected Customer Behaviour
- Assess Whether Transaction Patterns Have a Clear Economic Purpose
- Apply Network Analytics to Connected Accounts and Individuals
- Link Cash Activity With Subsequent Fund Transfers
- Monitor Rapid Movement of Structured Deposits
- Strengthen Monitoring of Cash-Intensive Businesses
- Use Rolling-Time-Window Aggregation Rather Than Daily Thresholds Alone
- Investigate Repeated Threshold-Avoidance Patterns
- Integrate Structuring Indicators Into AML Transaction Monitoring
- Conduct Retrospective Reviews When New Intelligence Emerges
- Escalate Suspicious Patterns Even Where Individual Transactions Appear Ordinary
- Treat Structuring Detection as a Behavioural Pattern-Recognition Challenge
Ultimately, structuring is important in the financial crime environment because it is a deliberate attempt to defeat one of the financial system’s core transparency controls. It is not just small transactions; it is the intentional fragmentation of activity to avoid detection, reporting, or recordkeeping. For that reason, structuring should be treated as a serious AML red flag and a direct challenge to the integrity of regulatory reporting controls.