Promotional abuse is a form of fraud in which a person exploits offers such as sign-up bonuses, referral rewards, discounts, vouchers, cashback offers, loyalty benefits, or free-trial incentives in ways that breach the intended rules of the promotion. Industry glossaries describe it as exploiting promotional offers for financial gain, often through multiple accounts, self-referrals, repeated code use, or other manipulation of offer terms.
Key Takeaways
- Promotional Abuse Exploits Legitimate Incentive Programmes for Unintended Financial Gain
- Welcome Bonuses Are a Common Target for Promotional Abuse
- Referral Schemes Can Be Manipulated Through Fake or Controlled Accounts
- Cashback Offers Can Be Exploited Through Artificial Transaction Activity
- Multiple Account Creation Is a Core Promotional Abuse Typology
- Synthetic or Stolen Identities Can Be Used to Circumvent Eligibility Rules
- Device Sharing Can Reveal Coordinated Promotional Abuse
- Fraudsters May Use Multiple Email Addresses and Phone Numbers to Appear Unrelated
- Self-Referral Can Convert Promotional Incentives Into Direct Financial Gain
- Collusive Groups Can Scale Abuse Across Large Numbers of Accounts
- Mule Accounts Can Support the Collection and Movement of Promotional Proceeds
- Promotional Abuse Can Overlap With Application and Identity Fraud
- Transaction Reversals Can Be Used to Retain Rewards Without Genuine Economic Activity
- Artificial Spending Can Be Created Solely to Trigger Incentive Thresholds
- Promotional Abuse Can Affect Banks, Fintechs, E-Commerce Platforms and Gaming Businesses
- Individual Accounts May Appear Legitimate When Reviewed in Isolation
- Network Analysis Can Reveal Hidden Connections Between Abusive Accounts
- Static Eligibility Rules Can Be Circumvented by Adaptive Fraudsters
- Promotional Abuse Can Create Direct Financial Loss and Distort Customer Acquisition Metrics
- Effective Detection Requires Identity, Device, Behavioural and Transaction Intelligence
In the financial crime environment, promotional abuse matters because it is more than ordinary customer opportunism. In serious cases, it becomes a structured fraud typology involving false identities, synthetic or duplicate accounts, device manipulation, collusion, stolen payment credentials, and laundering of promotional value through goods, credits, or resale. Industry sources note that fraudsters may create many fake accounts in a short period to redeem the same promotion repeatedly, and Experian highlights use of cloned apps, emulators, and fake accounts to exploit new-customer offers at scale.
From a professional perspective, the key issue is that promotional abuse often targets business logic rather than payment rails alone. The fraudster is not necessarily attacking a bank account directly at first. Instead, they exploit weaknesses in how a platform applies eligibility rules, validates account uniqueness, links referrals, enforces voucher conditions, or measures customer legitimacy. FraudNet’s business-logic-fraud material specifically cites exploitation of promotional codes as an example of control weakness where single-use or restricted offers are reused improperly.
Watch on YouTube: Promotional Abuse
This is why promotional abuse sits at the intersection of first-party fraud, identity misuse, account farming, and platform abuse. A fraudster may use their real identity dishonestly, may create fake or synthetic identities, or may use stolen information to generate additional accounts. Unit21’s and other industry descriptions show that duplicate-account creation is a common mechanism, while FraudNet’s coupon-discount-abuse material focuses on repeated use of promotions beyond intended limits.
In practical terms, common forms of promotional abuse include repeated sign-up bonus claims, self-referrals disguised as genuine referrals, exploitation of introductory pricing, repeated use of one-time discount codes, loyalty-benefit manipulation, and abuse of free-trial or cashback structures. Several industry sources describe promo abuse in exactly these terms, especially around sign-up incentives, referral bonuses, and loyalty discounts.
The typology is especially relevant in digital businesses because low-friction onboarding and automated promotions make scale easier for fraudsters. Experian notes that industries such as food delivery and ride-hailing are particularly vulnerable, and describes the use of automated or emulated environments to create large numbers of accounts and monetize promotional offers.
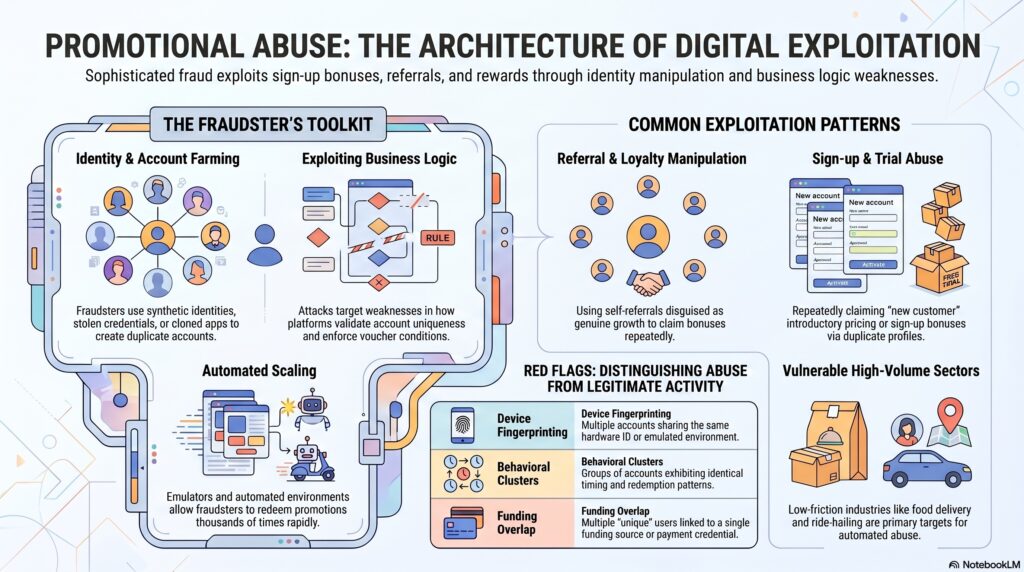
For firms, the control challenge is that promotional abuse can look superficially like ordinary customer acquisition activity. A sign-up may seem genuine, a discount redemption may appear valid, and a referral may look legitimate in isolation. The risk becomes visible when firms connect patterns such as shared devices, reused contact points, linked funding sources, repeated credential changes, unusual redemption timing, or clusters of accounts behaving alike. FraudNet and other industry sources point to repetitive account openings and offer exploitation as key indicators.
A mature control response therefore requires more than checking whether a promo code works technically. It usually involves identity controls, device and behavioral analytics, referral-link analysis, linked-account detection, abuse-rate monitoring, and governance over how promotions are designed and enforced. Industry guidance consistently frames promotional abuse as a fraud problem created by weak eligibility and validation controls, not just by dishonest customers.
What Financial Institutions Should Consider
- Define Clear Promotional Abuse Risk Scenarios
- Strengthen Identity Verification for Incentive-Eligible Accounts
- Detect Multiple Accounts Linked to Common Devices
- Monitor Shared Contact and Payment Information
- Identify Self-Referral Patterns
- Analyse Referral Networks for Circular Relationships
- Detect Artificial Transactions Designed to Trigger Rewards
- Monitor Rapid Reward Redemption
- Review Transactions Reversed Shortly After Incentives Are Earned
- Identify Repeated Account Opening and Closure Patterns
- Monitor Promotional Activity Across Related Customers
- Apply Device Intelligence to Multi-Account Detection
- Use Behavioural Analytics to Identify Incentive-Driven Activity
- Apply Graph Analytics to Connected Accounts and Referrals
- Strengthen Synthetic Identity Detection
- Monitor Mule Accounts Receiving Promotional Proceeds
- Integrate Promotional Abuse With Wider Fraud Monitoring
- Feed Confirmed Abuse Outcomes Back Into Detection Models
- Balance Customer Acquisition With Fraud-Control Effectiveness
- Treat Promotional Abuse as a Networked Fraud Risk Rather Than a Marketing Issue Alone
I should note one limitation: this term appears primarily in industry glossaries and fraud-prevention materials, not as a formal regulatory definition. So promotional abuse is best understood as an industry fraud label rather than a standardized legal term. The meaning is still fairly consistent across sources: exploitation of promotional offers for improper financial gain.