Synthetic fraud, more commonly called synthetic identity fraud, is a fraud typology in which criminals create a false identity by combining real personal information with fabricated information. The Federal Reserve’s interagency authentication guidance states that, unlike typical identity theft where a real person’s identity is stolen and used, a synthetic identity is a completely fabricated identity that does not correspond to any actual person. Industry and fraud-management sources often describe it as mixing a real identifier, such as a Social Security number, with a false name, date of birth, address, or other details to create a new identity.
Key Takeaways
- Synthetic Identity Fraud Combines Real and Fabricated Identity Elements
- Synthetic Identities Can Be More Difficult to Detect Than Fully Stolen Identities
- Criminals May Combine Genuine Personal Data With Invented Information
- Social Security Numbers or Other Identifiers Can Be Misused to Construct Synthetic Profiles
- Synthetic Identities Can Be Used to Open Bank and Credit Accounts
- Fraudsters May Build Credit History Before Monetising the Identity
- Bust-Out Fraud Is a Common Synthetic Identity Typology
- Synthetic Identities Can Remain Dormant or Low Risk for Extended Periods
- Individually Valid Data Points Do Not Prove That an Identity Is Genuine
- Weak Identity Resolution Can Allow Multiple Synthetic Profiles to Coexist
- Shared Devices, Addresses and Contact Details Can Reveal Connected Synthetic Identities
- Synthetic Identity Fraud Can Exploit Thin-File or Limited-Credit Customers
- Digital Onboarding Can Increase the Scale of Synthetic Identity Attacks
- AI-Generated Documents and Deepfakes Can Strengthen Synthetic Identity Fraud
- Synthetic Identities Can Be Used to Create Mule or Pass-Through Accounts
- Fraud Proceeds Can Feed Into Wider Money Laundering activity
- Traditional KYC Checks May Miss Coherent but Fabricated identity narratives
- Behavioural and network analysis Can Reveal Signals Not Visible During Onboarding
- Synthetic Identity Risk Extends Across Fraud, Credit, AML and Cyber Controls
- Effective Detection Requires Identity, Device, Behavioural and Relationship Intelligence
In the financial crime environment, synthetic identity fraud matters because it attacks one of the basic assumptions of financial services: that the identity presented at onboarding corresponds to a real, knowable person. With synthetic identity fraud, the criminal does not always impersonate an existing customer in the traditional sense. Instead, they manufacture a customer that appears credible enough to pass parts of the onboarding, credit, or servicing process. That makes the typology especially dangerous in lending, payments, cards, deposit accounts, and digital onboarding environments. This is an inference supported by the Federal Reserve’s distinction between synthetic identities and traditional stolen-identity fraud.
A key professional distinction is that synthetic identity fraud differs from ordinary identity theft. The CFPB’s regulation defines identity theft as a fraud committed or attempted using the identifying information of another person without authority. Synthetic identity fraud may involve misuse of a real identifier, but the overall identity is often not a real existing person in full. That is why the typology can be harder to detect and harder to remediate than standard true-name identity theft.
Watch on YouTube: Synthetic Fraud or Synthetic Identity Fraud
From a professional perspective, the fraud often develops over time rather than in a single event. A synthetic identity may first be used to open a low-risk account or obtain a small amount of credit. The fraudster may then cultivate that identity by creating transaction history, establishing repayment behavior, or building a credit profile before “busting out” with larger fraud, unpaid balances, or rapid misuse. While the exact lifecycle varies, the underlying control problem is consistent: the institution is dealing with an identity that appears plausible but is fundamentally false. This is an inference supported by common industry descriptions of synthetic identity fraud as the creation of a “new” identity from mixed real and fake data.
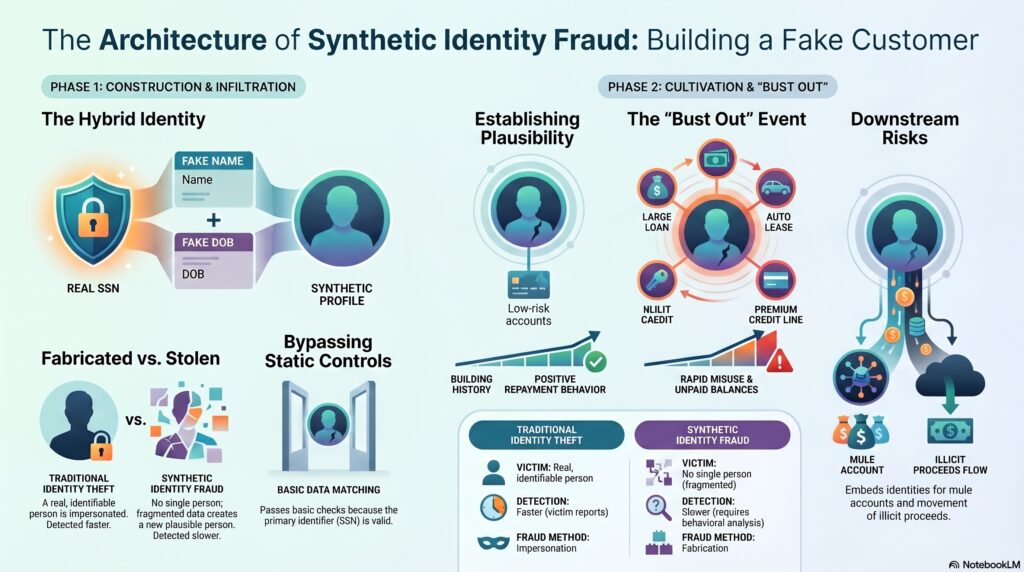
This typology is important in the financial crime environment because it sits at the intersection of identity fraud, application fraud, account abuse, and wider illicit-finance risk. A synthetic identity can be used to obtain credit, payment instruments, account access, or transactional infrastructure that later supports other frauds or movement of illicit proceeds. In that sense, synthetic identity fraud is not only an onboarding problem. It can become a downstream fraud, mule-account, or suspicious-activity issue once the false identity is embedded in the financial system. This is an inference drawn from how synthetic identities are created and then used to commit fraud.
For firms, the core challenge is that synthetic identities can pass controls that focus too narrowly on document presenceor basic data matching. A real identifier paired with fabricated details may produce a partial appearance of legitimacy. That means effective control usually requires more than static verification. It may require identity-resolution logic, behavioral analysis, cross-field consistency checks, linked-account analysis, device and contact-point review, and stronger scrutiny of thin-file or recently created identities. This is an inference supported by the Federal Reserve’s warning that synthetic identities are fabricated rather than straightforwardly stolen.
What Financial Institutions Should Consider
- Strengthen Identity Resolution During Onboarding
- Validate Identity Attributes Across Multiple Independent Sources
- Detect Inconsistent or Improbable Identity Combinations
- Monitor Reuse of Contact Details Across Multiple Customers
- Detect Shared Devices Across Apparently Unrelated Accounts
- Analyse Repeated Use of Common Addresses
- Strengthen Document Verification Controls
- Apply Liveness and Media Integrity Checks Where Appropriate
- Monitor AI-Generated Identity Document Risk
- Detect Early-Life Account and Credit Anomalies
- Monitor Gradual Credit-Building Followed by Sudden Bust-Out Behaviour
- Apply Behavioural Analytics Across the Customer Lifecycle
- Use Graph Analytics to Identify Synthetic Identity Networks
- Correlate Customer, Device, Account and Application Data
- Strengthen Fraud Monitoring for Thin-File Customers
- Integrate Synthetic Identity Risk Into Customer Risk Assessment
- Connect Fraud and AML Investigations
- Feed Confirmed Synthetic Fraud Cases Back Into Detection Models
- Conduct Retrospective Reviews When New Identity Intelligence Emerges
- Treat Synthetic Identity Detection as a Lifecycle and Network-Analysis Challenge
Ultimately, synthetic fraud or synthetic identity fraud is significant in the financial crime environment because it allows criminals to create a false customer that can interact with the financial system as if it were real. It is harder to detect than many traditional identity-fraud typologies because the identity may not belong fully to any one victim, and it can mature into broader fraud and illicit-value movement over time. For that reason, it should be treated as a distinct and serious identity-risk typology within fraud, onboarding, and financial crime control frameworks.