A politically exposed person (PEP) is an individual who is or has been entrusted with a prominent public function. FATF defines a PEP in those terms and explains that such positions can be abused for money laundering, corruption, bribery, and related predicate offences, which is why additional AML/CFT measures are required for business relationships involving PEPs.
Key Takeaways
- A Politically Exposed Person Is Someone Entrusted With a Prominent Public Function
- PEP Status Reflects Elevated Corruption and Money Laundering Risk Rather Than Presumed Wrongdoing
- PEP Classification Should Trigger Enhanced Scrutiny Rather Than Automatic Rejection
- Foreign PEPs Commonly Attract Higher Regulatory Expectations
- Domestic PEPs Should Be Assessed Through a Proportionate Risk-Based Approach
- Former PEPs Can Continue to Present Residual Risk
- Family Members Can Be Relevant to PEP Risk Assessment
- Close Associates Can Also Create Indirect PEP Exposure
- Public Influence Can Be Misused for Bribery, Embezzlement or Abuse of Office
- PEP Risk Can Extend Through Companies, Trusts and Other Legal Structures
- Beneficial Ownership Analysis Is Critical to Identifying Hidden PEP Connections
- Source of Wealth Is a Core PEP Due Diligence Consideration
- Source of Funds Should Be Consistent With the Customer’s Profile and Wealth
- Senior Management Approval Can Be Required for PEP Relationships
- Ongoing Monitoring Is Essential Because PEP Risk Can Change Over Time
- Sanctions Exposure and PEP Exposure Should Be Assessed Separately
- Adverse Media Can Provide Important Context Around PEP Risk
- Jurisdiction, function and level of influence Should Shape the Risk Assessment
- PEP Screening Is Only the Starting Point of Effective PEP Risk Management
- Effective PEP Controls Require Proportionate, Risk-Based Enhanced Due Diligence
In the financial crime environment, the importance of a PEP lies not in status alone, but in the elevated risk that public power, influence, and access to state resources may be misused for private gain. A PEP is not presumed to be corrupt or suspicious simply because of their office. The issue is that prominent public functions can create greater exposure to bribery, embezzlement, abuse of office, sanctions-adjacent risks, and concealment of illicit wealth. FATF’s PEP materials link the regime directly to these corruption and money laundering vulnerabilities.
From a professional AML perspective, PEP classification is a risk-based trigger for enhanced scrutiny, not an automatic ground for refusal. FATF Recommendation 12 requires additional measures for foreign PEPs, and the UK Money Laundering Regulations require enhanced customer due diligence and enhanced ongoing monitoring in relation to PEPs. In the UK, the legislation now distinguishes between domestic PEPs and non-domestic PEPs.
Watch on YouTube: Politically Exposed Person (PEP)
That distinction matters because current UK guidance emphasizes a proportionate and risk-based approach, especially for domestic PEPs. The FCA’s finalised 2025 guidance says firms should apply a proportionate and risk-based approach to UK PEPs, their relatives, and close associates, rather than treating all PEP relationships as uniformly high risk. In practical terms, that means firms should avoid mechanical treatment and instead assess the actual money laundering risk presented by the person, the relationship, and the surrounding circumstances.
PEP risk also extends beyond the office-holder personally. FATF and UK AML frameworks recognize the relevance of family members and close associates, because illicit funds or influence may be routed through people connected to the PEP rather than through the PEP directly. This is why firms often screen not only the principal individual but also linked persons and ownership structures associated with them.
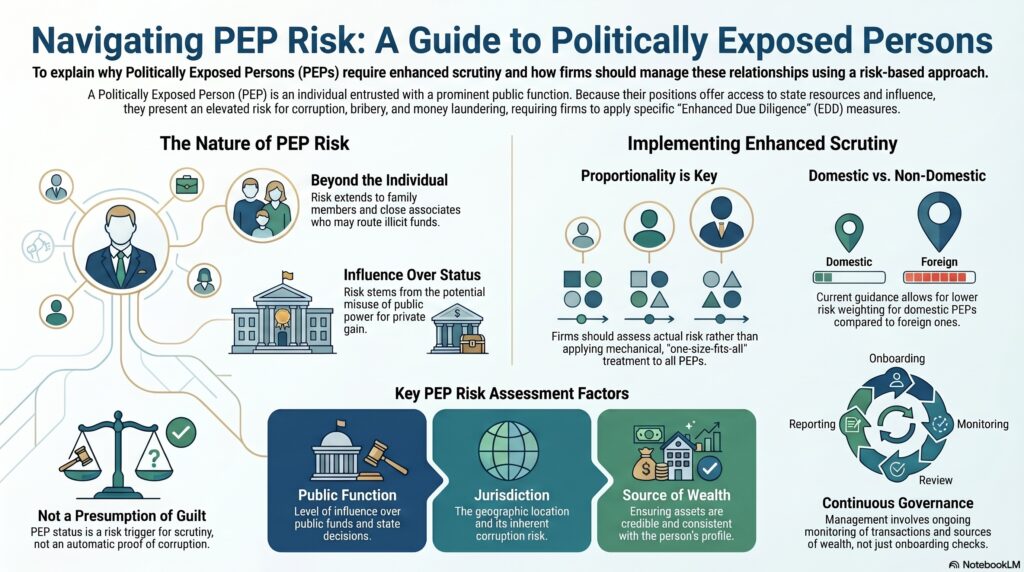
In practical financial crime terms, PEP risk assessment usually focuses on questions such as: what public function does the person hold or have they held, in what jurisdiction, with what level of influence over public funds or state decisions, through what structures do they hold assets or control companies, and whether source of wealth and source of funds are credible and consistent with the profile. FATF’s guidance and the UK regulatory framework both support enhanced scrutiny around these areas.
This is why PEP controls are closely tied to customer due diligence, beneficial ownership, source-of-wealth assessment, sanctions screening, and ongoing monitoring. A PEP may use companies, trusts, intermediaries, or relatives to hold assets or conduct transactions, and the risk can change over time depending on office, influence, and geography. For firms, that means PEP handling is not just an onboarding classification exercise; it is a continuing governance and monitoring issue. This is an inference supported by FATF’s PEP guidance and the UK’s EDD requirements for PEPs.
What Financial Institutions Should Consider
- Maintain Clear PEP Identification and Classification Criteria
- Distinguish Domestic, Foreign and International Organisation PEPs
- Identify Relevant Family Members and Close Associates
- Verify PEP Screening Matches Before Escalation
- Assess the Nature and Seniority of the Public Function
- Evaluate the Jurisdiction Associated With the PEP
- Understand the Customer’s Source of Wealth
- Verify Source of Funds for Relevant Transactions
- Identify Companies and Structures Controlled by the PEP
- Strengthen Beneficial Ownership Analysis
- Assess Connections to State-Owned Enterprises and Public Funds
- Review Adverse Media and Corruption Allegations
- Screen Separately for Sanctions Exposure
- Obtain Appropriate Senior Management Approval
- Apply Enhanced Ongoing Monitoring Where Required
- Monitor Transactions Against the Expected Customer Profile
- Conduct Event-Driven Reviews Following Changes in Public Office
- Reassess Risk After the Individual Leaves Public Office
- Avoid Automatic De-Risking Based Solely on PEP Status
- Treat PEP Risk as a Dynamic Corruption and Financial Crime Exposure
Ultimately, a politically exposed person is important in the financial crime environment because the role captures a category of customer who may present higher corruption-linked and money laundering risk due to prominent public power or influence. The correct professional response is neither automatic suspicion nor automatic acceptance. It is proportionate, risk-based enhanced due diligence designed to ensure that the relationship is understood, justified, and monitored appropriately.