A nested account is an account or relationship in which one financial institution gains access to another institution’s correspondent banking services through an intermediary institution rather than directly. The Wolfsberg Group explains nested relationships as arrangements where a respondent bank uses another financial institution’s correspondent account to access the payment system, and FATF’s correspondent banking guidance discusses the same risk under the broader issue of downstream or indirect access.
Key Takeaways
- Nested Accounts Create Indirect Access to Correspondent Banking Services
- The Direct Correspondent May Not Have a Relationship With the Underlying Nested Institution
- Nested Banking Can Increase Customer and Transaction Transparency Challenges
- Correspondent Banks May Have Limited Visibility Into Downstream Institutions
- Nested Relationships Can Extend Across Multiple Jurisdictions
- Legitimate Nested Structures Can Support Cross-Border Financial Access
- Nested Accounts Are Not Inherently Suspicious
- Risk Increases When Downstream Institutions Have Weak AML Controls
- Indirect Access Can Create Sanctions Screening Challenges
- Customer Due Diligence Becomes More Complex Across Multiple Banking Layers
- Poor Transparency Can Obscure the Originator or Beneficiary of Payments
- Nested Structures Can Be Exploited to Move Criminal Proceeds
- Higher-Risk Jurisdictions Can Increase Nested Banking Exposure
- Shell Banks Can Create Significant Risk Within Correspondent Networks
- Payment Messages Alone May Not Reveal the Full Banking Chain
- Ownership and Control of Downstream Institutions Are Important Risk Factors
- Nested Activity Can Change Without Formal Changes to the Direct Relationship
- Ongoing Monitoring Is Essential to Detect Unexpected Downstream Usage
- Correspondent Banking Risk Depends on Transparency, Controls and Network Structure
- Effective Nested Account Risk Management Requires Understanding the Full Payment Chain
In the financial crime environment, nested accounts matter because they create an additional layer of distance between the institution providing payment access and the institution or customer ultimately using that access. That extra layer can reduce transparency over who is sending or receiving funds, what controls apply downstream, and whether higher-risk activity is entering the payment chain through a respondent the correspondent does not know directly. FATF’s guidance on correspondent banking stresses that correspondents need to understand the respondent’s business, controls, and access arrangements as part of a risk-based approach.
Watch on YouTube: Nested Account
From a professional perspective, the core risk is not that nesting is automatically improper. Nested arrangements can arise for legitimate commercial reasons, especially where smaller institutions rely on larger institutions for access to cross-border payments or major clearing systems. The real issue is whether the correspondent has enough visibility into the respondent’s downstream relationships and control environment to understand who may be using the account indirectly. Wolfsberg notes that nested activity can create heightened AML and sanctions risk where transparency is weak or where downstream institutions are not adequately understood.
This matters because nested accounts can be used to introduce higher-risk customers, institutions, or jurisdictions into a payment flow without a direct relationship between the end participant and the correspondent bank. If the respondent’s customer due diligence, sanctions screening, or transaction monitoring is weak, the correspondent may end up processing activity it would not have accepted directly. In that sense, nested accounts are mainly a control and visibility issue within correspondent banking rather than a standalone product type. This is an inference supported by FATF’s emphasis on respondent due diligence and risk-based monitoring in correspondent relationships.
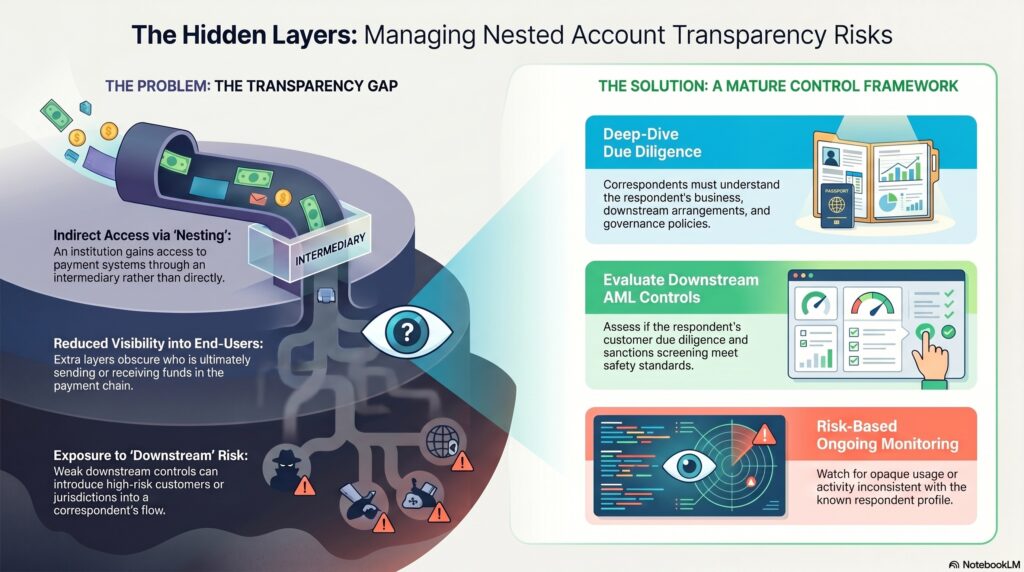
A mature control framework therefore requires the correspondent to understand whether nesting is permitted, how it is governed, what kinds of downstream institutions or customers may have indirect access, and whether the respondent’s AML, sanctions, and monitoring controls are strong enough to manage that activity. Where nested usage is opaque, inconsistent with the respondent profile, or linked to higher-risk corridors, the risk of money laundering, sanctions evasion, fraud proceeds movement, and other illicit activity increases materially.
What Financial Institutions Should Consider
- Identify Whether Correspondent Relationships Permit Nested Access
- Understand the Respondent Bank’s Downstream Customer Base
- Assess the Respondent’s AML and Sanctions Control Framework
- Identify Downstream Financial Institutions Where Risk Warrants
- Review Jurisdictions Accessed Through Nested Relationships
- Strengthen Due Diligence on Higher-Risk Correspondent Relationships
- Assess Ownership and Control of Respondent Institutions
- Screen for Shell Bank Exposure
- Understand Expected Payment Corridors and Transaction Volumes
- Monitor Activity for Unexpected Downstream Institutions
- Detect Material Changes in Correspondent Banking Behaviour
- Analyse Originator and Beneficiary Transparency
- Review Payment Messages for Missing or Incomplete Information
- Monitor Transactions Involving Higher-Risk Jurisdictions
- Integrate Sanctions Screening With Correspondent Banking Monitoring
- Apply Network Analytics to Multi-Bank Payment Chains
- Conduct Periodic and Event-Driven Correspondent Reviews
- Escalate Unexplained Nested Activity
- Avoid Blanket De-Risking Where Risks Can Be Effectively Managed
- Treat Nested Banking as a Transparency and Network-Risk Challenge
Ultimately, a nested account is significant in the financial crime environment because it can allow value to move through the banking system indirectly, making transparency and control more difficult. For that reason, nested arrangements should be understood as a key correspondent-banking risk area requiring strong due diligence, ongoing monitoring, and clear governance over downstream access.