“Designated categories of offense” is a term used in the FATF standards to describe the minimum categories of predicate crimes that countries should cover when criminalising money laundering. FATF Recommendation 3 says countries should apply the crime of money laundering to all serious offenses, and at a minimum include offenses within each designated category.
Key Takeaways
- Designated Categories of Offense Define the Minimum FATF Predicate Crime Universe
- Money Laundering Depends on Underlying Criminal Conduct
- Predicate Offences Extend Far Beyond Drug Trafficking
- Fraud Is a Major Money Laundering Predicate Offence
- Bribery and Corruption Can Generate Launderable Criminal Proceeds
- Tax Crimes Form Part of the FATF Predicate Offence Framework
- Human Trafficking and Migrant Smuggling Generate Significant Illicit Proceeds
- Environmental Crime Is Recognised as a Predicate Crime Category
- Terrorism and Terrorist Financing Sit Within the FATF Framework
- Insider Trading and Market Manipulation Can Generate Criminal Proceeds
- Smuggling and Illicit Trade Create Cross-Border Laundering Exposure
- Organised Crime and Racketeering Remain Core Predicate Risks
- Financial Institutions Must Understand the Crime Behind the Money
- Transaction Monitoring Should Reflect a Broad Range of Predicate Typologies
- Narrow AML frameworks Can Miss Significant Sources of Criminal Wealth
- Predicate-Offence Intelligence Strengthens AML Investigations and Escalation
In the financial crime environment, the concept matters because money laundering does not exist in isolation. It depends on an underlying crime that generates illicit proceeds. Those underlying crimes are commonly called predicate offenses. The FATF glossary links “criminal activity” to offenses that would constitute predicate offenses for money laundering, and the designated categories define the minimum range of those crimes that legal systems should capture.
Watch on YouTube: Designated Categories of Offense
This is important from a compliance and enforcement perspective because the breadth of predicate offenses determines how widely the AML framework can operate. If a jurisdiction defines predicate offenses too narrowly, criminals may still generate proceeds from serious misconduct that falls outside the local money laundering regime. By requiring coverage across designated categories, FATF is trying to ensure that AML laws can attach to a broad spectrum of serious criminal conduct rather than only to a few traditional offenses.
The FATF glossary currently lists the designated categories of offenses as including: participation in an organised criminal group and racketeering; terrorism, including terrorist financing; trafficking in human beings and migrant smuggling; sexual exploitation; illicit trafficking in narcotic drugs and psychotropic substances; illicit arms trafficking; illicit trafficking in stolen and other goods; corruption and bribery; fraud; counterfeiting currency; counterfeiting and piracy of products; environmental crime; murder and grievous bodily injury; kidnapping, illegal restraint and hostage-taking; robbery or theft; smuggling, including customs and excise and tax-related smuggling; tax crimes relating to direct and indirect taxes; extortion; forgery; piracy; and insider trading and market manipulation. FATF notes that the glossary definition was revised in October 2021 to clarify the environmental crime category.
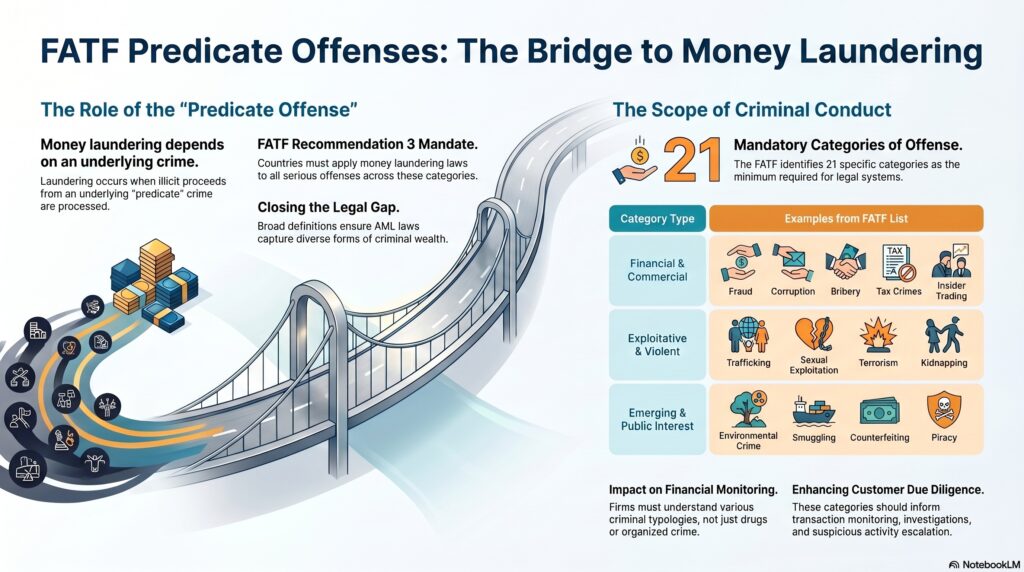
For financial institutions, this concept is not just legal background. It affects how firms understand the sources of criminal proceeds they may encounter. If fraud, corruption, tax crime, trafficking, environmental crime, or market manipulation are predicate offenses, then the proceeds of those acts can become the subject of money laundering concerns. That means transaction monitoring, customer due diligence, investigations, and suspicious activity escalation should be informed by a broad understanding of criminal typologies rather than a narrow focus on drugs or organized crime alone. This is an inference from FATF’s requirement that money laundering apply to the widest range of predicate offenses and from the breadth of the designated categories.
What Financial Institutions Should Consider
- Incorporate Predicate Offences Into Enterprise-Wide AML Risk Assessments
- Map Relevant Predicate Crimes to Customer and Product Exposure
- Integrate Fraud Typologies Into AML Monitoring
- Strengthen Bribery and Corruption Risk Detection
- Include Tax Crime Indicators in Financial Crime Monitoring
- Monitor Human Trafficking and Exploitation Typologies
- Incorporate Environmental Crime Risk Where Relevant
- Strengthen Organised Crime and Racketeering Indicators
- Monitor Smuggling and Illicit Trade Exposure
- Integrate Market Abuse Intelligence With AML Controls
- Connect Cybercrime Proceeds With Money Laundering Monitoring
- Identify the Suspected Source of Criminal Proceeds During Investigations
- Link Customer Risk Assessments to Relevant Predicate Threats
- Apply Network Analytics to Connected Criminal Activity
- Strengthen Cross-Functional Fraud, AML and Market Conduct Intelligence
- Update Typology libraries as Criminal Threats Evolve
- Train Investigators on a Broad Range of Predicate Offences
- Avoid Focusing AML Controls Only on Traditional Money Laundering Typologies
- Use Predicate-Offence Context to Improve Suspicious Activity Reporting
- Treat Underlying Criminal Conduct as a Core Dimension of AML Risk
Ultimately, designated categories of offense are important in the financial crime environment because they define the minimum universe of serious criminal conduct that should feed into AML law. They are the bridge between predicate crime and the laundering of criminal proceeds. Without that bridge, a jurisdiction’s AML regime may look complete on paper while leaving significant forms of criminal wealth outside the money laundering framework.